The Iranian Rial is the weakest currency in the world in 2026 when currencies are ranked by the number of local units needed to buy one US dollar. On October 7, one dollar cost about 2.69 million rials on Iran’s open market.
Lebanon is a distant second at 89,500 pounds per dollar. Vietnam, Laos, Indonesia, Uzbekistan, and Guinea follow, although the reasons behind those exchange rates are very different.
That difference is the key to reading the ranking properly. Iran and Lebanon have suffered huge losses in currency value. Vietnam has not. One dollar already bought more than 20,000 Vietnamese dong a decade ago, and the economy has continued to expand since then.
So a currency does not belong high on this list because its economy is automatically weak. The ranking simply counts how many local currency units are needed for one dollar.
| Rank | Currency | Country | Rate for 1 USD | Rate Used | Source |
|---|---|---|---|---|---|
| 1 | Iranian Rial (IRR) | Iran | 2,690,000 IRR | Open market, October 7, 2026 | Artesh market history |
| 2 | Lebanese Pound (LBP) | Lebanon | 89,500 LBP | Reference rate, 2026 | Banque du Liban |
| 3 | Vietnamese Dong (VND) | Vietnam | 25,980 VND | Market rate, early October 2026 | Historical USD/VND data |
| 4 | Laotian Kip (LAK) | Laos | 22,368 LAK | Reference rate, October 7, 2026 | Bank of the Lao P.D.R. |
| 5 | Indonesian Rupiah (IDR) | Indonesia | 17,910 IDR | JISDOR, October 6, 2026 | Bank Indonesia |
| 6 | Uzbekistani Som (UZS) | Uzbekistan | 11,790.79 UZS | Official rate, October 7, 2026 | Central Bank of Uzbekistan |
| 7 | Guinean Franc (GNF) | Guinea | About 8,779 GNF | Reference rate, October 6, 2026 | Central Bank of Guinea |
| 8 | Paraguayan Guarani (PYG) | Paraguay | 5,850.05 PYG | Interbank rate, October 6, 2026 | Central Bank of Paraguay |
| 9 | Malagasy Ariary (MGA) | Madagascar | 4,465.53 MGA | Reference rate, October 6, 2026 | Central Bank of Madagascar |
| 10 | Myanmar Kyat (MMK) | Myanmar | About 4,450 MMK | Parallel market, October 7, 2026 | Parallel-market history |
| 11 | Cambodian Riel (KHR) | Cambodia | 4,062 KHR | Official rate, October 7, 2026 | National Bank of Cambodia rate |
| 12 | Ugandan Shilling (UGX) | Uganda | About 4,030 UGX | Market reference, October 7, 2026 | Bank of Uganda |
| 13 | Mongolian Tugrik (MNT) | Mongolia | 3,595.55 MNT | Official rate, October 5, 2026 | Bank of Mongolia |
| 14 | Colombian Peso (COP) | Colombia | About 3,273 COP | TRM, early October 2026 | Banco de la República |
| 15 | Burundian Franc (BIF) | Burundi | 3,010.06 BIF | Official midpoint, October 7, 2026 | Bank of the Republic of Burundi |
| 16 | Tanzanian Shilling (TZS) | Tanzania | 2,635.57 TZS | Mean rate, October 7, 2026 | Bank of Tanzania |
The table is a snapshot taken from rates available between October 3 and October 7, 2026. Most rows use official or central-bank reference rates. Iran and Myanmar use parallel-market rates because their official dollar prices are far removed from what buyers pay outside controlled channels.
That choice is important. Mixing an official rate for Iran with a market rate for another country would produce a ranking that looks precise but compares two different things.
Nominal exchange rates also tell only part of the story, especially when compared with how much money exists in the world across cash, deposits and other forms of money.
1. Iranian Rial (IRR)
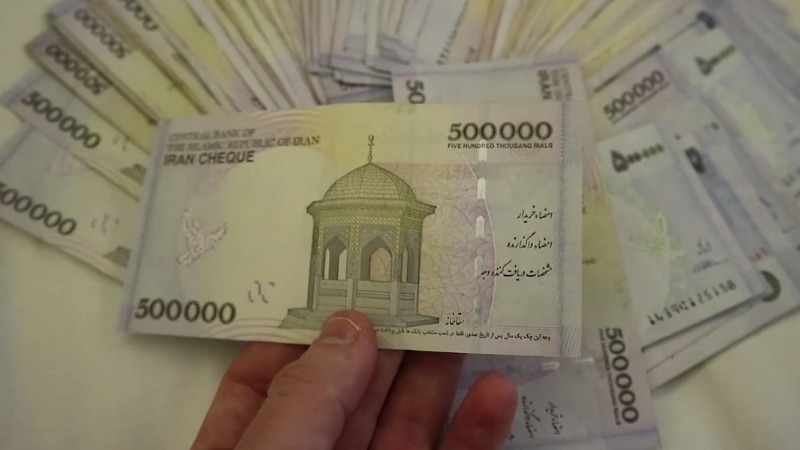
Iran is the clearest currency-crisis case in the ranking. The open-market dollar price reached about 2.69 million rials on October 7, far above the rates used for some official transactions.
That gap is not a technical curiosity. A business that cannot obtain enough dollars through an approved channel has to deal with the price available elsewhere. The same applies to households trying to protect savings from inflation.
Sanctions restrict oil sales, international banking, investment, and access to foreign currency. High inflation then adds pressure inside the country because holding savings in rials becomes increasingly expensive when prices keep rising.
The result is a self-reinforcing demand for dollars and other assets that hold value better. Iran therefore ranks first for a much more serious reason than simply issuing banknotes with many zeros.
The IMF country material for Iran continues to identify high inflation and external restrictions as major economic pressures. Iran’s next move will depend less on the printed denomination and more on inflation, oil revenue, sanctions, and access to usable foreign currency.
2. Lebanese Pound (LBP)
Lebanon is the other country near the top where the exchange rate itself tells a story of collapse. For years, the pound traded near 1,500 LBP per dollar. The current reference rate is 89,500.
The break came after the financial crisis that began in 2019. Banks could no longer provide depositors with normal access to dollars, the old exchange-rate system failed, and the pound lost most of its previous value.
Lebanon now uses far more dollars in everyday commerce than it did before the crisis. Prices for rent, services, and larger purchases are regularly quoted in dollars because businesses do not want to carry the exchange-rate risk themselves.
Inflation has dropped from the extreme levels recorded earlier in the crisis, but lower inflation does not restore the purchasing power that was already lost. That is the key point here. Stabilizing at 89,500 is not the same as returning to the old 1,500 rate.
Lebanon therefore sits second for a reason very different from Vietnam. The current number is the legacy of a banking and currency collapse, not simply an old denomination system.
3. Vietnamese Dong (VND)
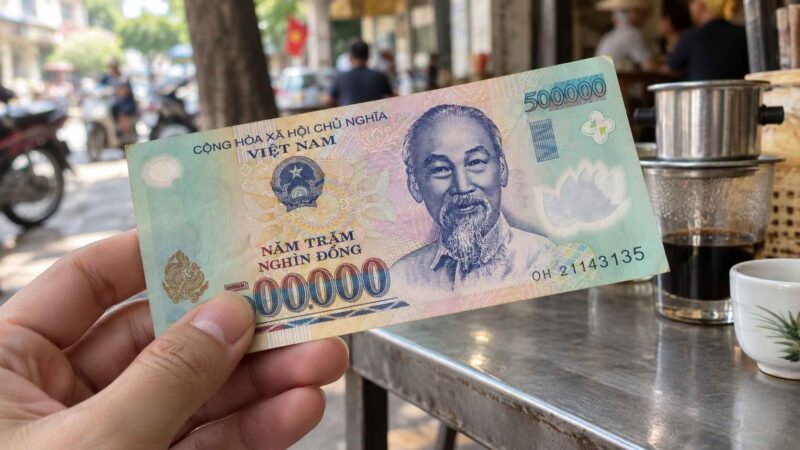
Vietnam is the entry that keeps the entire ranking honest. The dong is the third-lowest currency by nominal unit value, yet Vietnam has one of the strongest growth rates in the group.
The World Bank’s May 2026 economic update projected growth of 6.8% for 2026 after an 8% expansion in 2025.
One dollar buying almost 26,000 dong sounds dramatic only until local prices are converted. A 100,000-dong meal is worth less than four dollars at that rate.
The more useful question is how much the dong has moved over time. One dollar already bought roughly 22,000 dong in 2016. The rate is weaker today, but the change is nothing like the collapse seen in Lebanon.
Vietnam also earns large amounts of foreign currency from exports and foreign investment. Electronics, machinery, furniture, textiles, and other manufactured goods bring dollars into the economy.
So Vietnam belongs near the top of the nominal ranking, but calling the dong a crisis currency would be wrong. Its low unit value is mostly a denomination story with gradual depreciation layered on top.
4. Laotian Kip (LAK)
Laos sits between the crisis cases and the stable large-denomination currencies. The kip was already a low-value unit, but recent inflation and foreign-debt pressure pushed it further down.
Fuel is one of the clearest pressure points. Laos imports much of the energy it uses. When oil becomes more expensive, importers need more dollars and household transport costs rise soon afterward.
The World Bank’s June 2026 Lao Economic Monitor reported that inflation moved back toward 10% in April after energy prices rose. Growth for 2026 was projected at 3.8%.
Debt adds another problem because a large share has to be serviced in foreign currency. A weaker kip therefore makes some debt payments more expensive in local terms.
The authorities have tightened control over foreign-exchange activity and tried to rebuild reserves. Those steps helped calm the market compared with the worst period of depreciation, but Laos still has far less room for error than Vietnam or Indonesia.
5. Indonesian Rupiah (IDR)
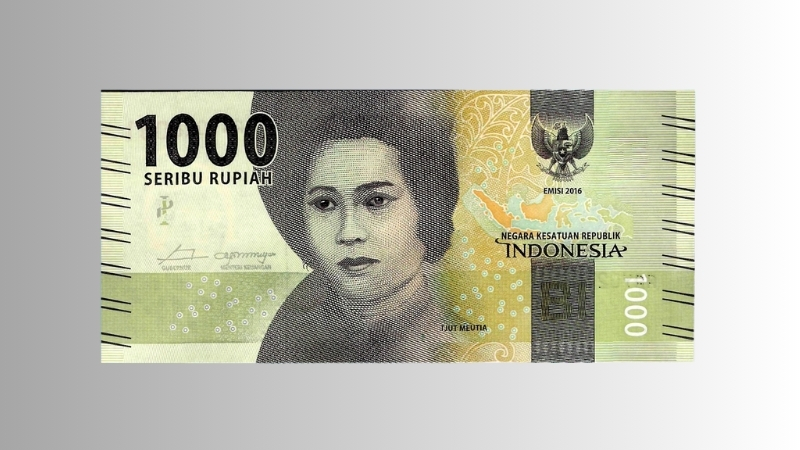
Indonesia is another case where the exchange-rate number looks more alarming than the economy behind it. Bank Indonesia’s JISDOR rate was 17,910 rupiah per dollar on October 6.
The more interesting 2026 story is what Bank Indonesia is doing around that rate. Its September indicators showed a policy rate of 5.75%, inflation of 3.19%, and foreign reserves of $146.5 billion. Bank Indonesia publishes those indicators together, which makes the contrast clear.
The rupiah weakened during periods of stronger dollar demand and higher global uncertainty, but Indonesia still has a large reserve buffer and a diversified export base.
Coal, palm oil, metals, manufactured goods, tourism, and other industries all bring foreign currency into the economy. The central bank can also use interest rates and market intervention when movements become too disruptive.
My read is simple. Indonesia belongs in the ranking because the rupiah is a small unit, not because the currency is close to breaking.
6. Uzbekistani Som (UZS)
Uzbekistan is not a clean depreciation story either. A large part of the jump in the som came from a deliberate change in how the country priced foreign currency.
Before 2017, Uzbekistan tightly controlled access to dollars. The official rate did not fully represent the price available outside the controlled system. Liberalization brought the official rate much closer to the market.
That is why the move from roughly 3,000 som per dollar in 2016 to more than 8,000 soon afterward should not be read as if the currency simply lost two-thirds of its real value overnight.
The country now has a sizable cushion. The World Bank reports that international reserves reached $70 billion in January 2026, with 86% held in gold. Growth is projected at 6.4% for 2026 and inflation below 8%.
Uzbekistan still faces energy-price exposure and inflation above the long-term target. Yet its current exchange rate is better described as the result of reform plus gradual depreciation than as evidence of monetary failure.
7. Guinean Franc (GNF)
Guinea has a low-value currency and an unusual growth story. The country is rich in bauxite, gold, diamonds, and iron ore, but much of the wider economy remains poor and underdeveloped.
The Simandou iron ore project changes the outlook because it can bring a much larger stream of export dollars into the country. That is potentially positive for the franc, reserves, tax revenue, and growth.
Inflation is also far lower than the old 30% to 40% figures sometimes attached to Guinea online. The World Bank reports 3.2% inflation in 2025 and projects 4.7% in 2026.
The weakness is concentration. Mining dominates foreign earnings, so commodity prices and the timing of major projects can have an outsized effect on the currency.
Guinea therefore has a low-value franc, but the 2026 story is not runaway inflation. It is a mineral economy trying to turn export wealth into a stronger financial base.
8. Paraguayan Guarani (PYG)
Paraguay is the biggest surprise in the list. The guaraní is one of the lowest-value units in South America, yet it has been one of the stronger currencies against the dollar recently.
The IMF’s 2026 Article IV review says the guaraní appreciated 23.1% year over year by June and 8.6% from the beginning of 2026 to that point.
The same review put inflation at 2.1% in June and projected 4.4% economic growth for the year. Net international reserves stood near $11 billion.
Agricultural exports, beef, and hydroelectric power bring foreign currency into Paraguay. When export income is strong, the central bank has less pressure to defend the guaraní.
So Paraguay is not merely an exception to the ranking. It is evidence that the ranking can point in the opposite direction from current currency performance. The unit is small, but the currency itself has recently strengthened.
9. Malagasy Ariary (MGA)
Madagascar’s ariary sits around 4,466 per dollar, but the exchange rate is not the sharpest problem households face.
Inflation was 8.6% in June 2026 according to the Central Bank of Madagascar. That affects food, transport, and household budgets immediately, even if the exchange rate itself changes only gradually.
The country earns dollars from vanilla, nickel, cobalt, textiles, tourism, and other exports. Fuel, machinery, medicines, and food imports pull foreign currency in the opposite direction.
Madagascar also has limited room to absorb shocks because incomes remain low and infrastructure is weak. A rise in fuel prices therefore reaches households more quickly than it would in a richer economy.
The ariary deserves a place in the ranking, but its real problem is not the four-digit number. Inflation and low household purchasing power are far more useful measures of the pressure people feel.
10. Myanmar Kyat (MMK)
Myanmar is the hardest currency here to rank cleanly because there is no single dollar price that describes the market.
The official reference rate remains near 2,100 kyat per dollar. Parallel-market data around October 7 put the rate near 4,450. That means buyers outside official channels were paying more than twice the controlled price.
A gap that large tells you the official rate is not clearing the full demand for dollars. Businesses that cannot obtain enough foreign currency at the controlled price have an incentive to move elsewhere.
War, foreign-exchange controls, electricity shortages, weak investment, and disruption since the 2021 military takeover have all added pressure. The World Bank has repeatedly described Myanmar as an economy operating under severe conflict and supply constraints.
Myanmar therefore deserves a different label from Vietnam or Paraguay. The core issue is not denomination. It is a fragmented foreign-exchange market where the official price and the available price can be radically different.
11. Cambodian Riel (KHR)
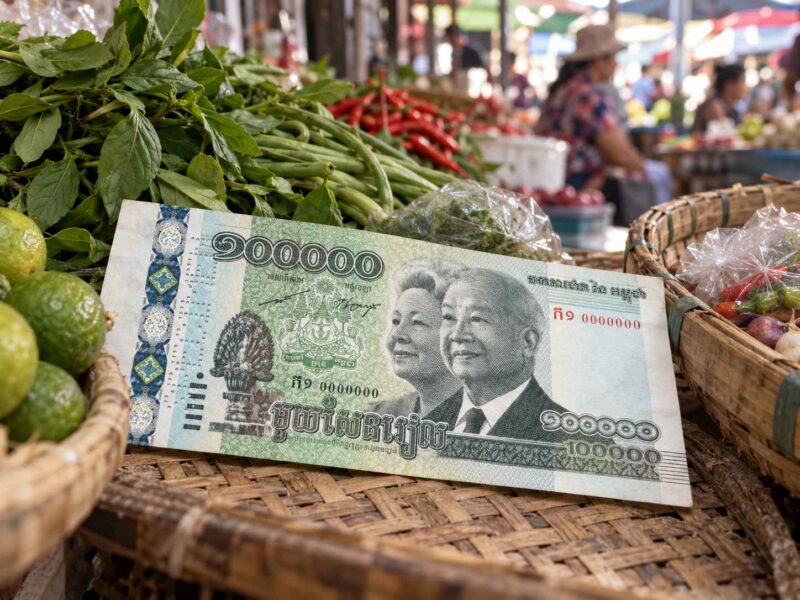
Cambodia keeps the riel close to 4,000 per dollar, and that stability is deliberate.
The country is also highly dollarized. Dollars circulate alongside riel, particularly for larger payments, rent, tourism, and business transactions.
That changes the role of the local currency. Cambodia does not rely on the riel alone for the financial system, so a four-digit USD rate has less practical meaning than it would in a country where virtually every transaction stays in local currency.
The World Bank expects growth of 3.9% in 2026 after weaker global conditions, fuel costs, and softer remittance flows weighed on the economy.
The riel is therefore one of the least dramatic entries on the list. Its low nominal value has persisted for years without a currency collapse.
12. Ugandan Shilling (UGX)
Uganda is more interesting for what could happen next than for its current four-digit exchange rate.
The country is moving toward commercial oil production. If exports ramp up as planned, they should bring in a new source of dollar revenue and change Uganda’s balance of payments.
Inflation remains relatively contained. The World Bank reported 4.1% in August 2026, below the central bank target of 5%.
The risk is that oil does not automatically strengthen a currency. Large infrastructure imports, debt service, and profit transfers can also create demand for dollars. The timing of production and investment flows therefore counts.
Uganda’s shilling looks weak by unit value, but the next few years will be shaped more by oil revenue and fiscal policy than by the number 4,000 itself.
13. Mongolian Tugrik (MNT)
Mongolia’s currency is tied closely to one economic relationship. China buys most of the country’s coal and copper exports.
That makes the tugrik sensitive to Chinese construction, industry, commodity demand, and border trade. Strong mineral exports bring dollars and yuan into Mongolia. A slowdown can remove that support quickly.
The World Bank expects growth near 5% in 2026. Mining remains the engine, with agriculture adding another source of output after earlier weather shocks.
For the central bank, the difficult balance is inflation versus growth. Higher rates can support the tugrik and slow prices, but expensive credit also restrains businesses and households.
Mongolia’s exchange rate therefore tells a more interesting story than “3,600 tugrik equals one dollar.” The real variable to watch is export income from China.
14. Colombian Peso (COP)
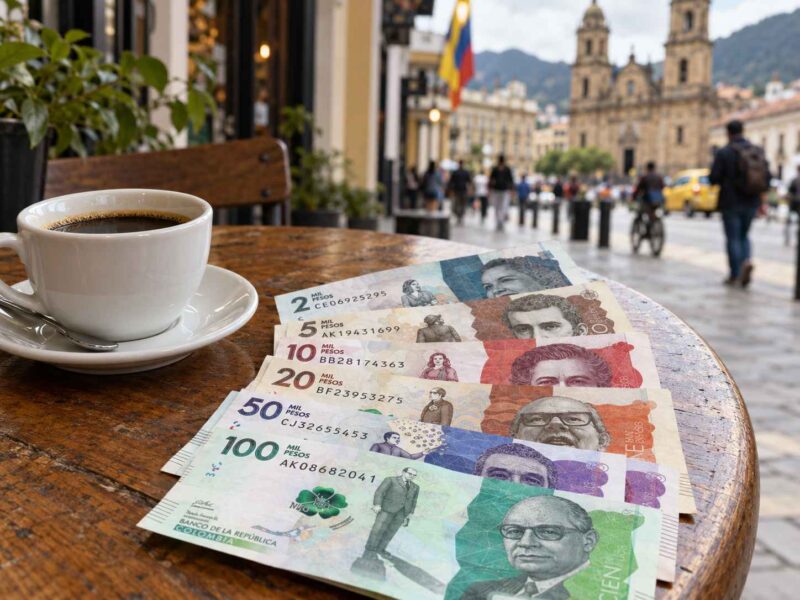
Colombia is the most market-driven currency near the bottom of the ranking. The peso floats, so it can move sharply when oil prices, US rates, politics, or investor expectations change.
Monetary policy became especially important in 2026. Banco de la República raised its benchmark rate from 9.25% in December 2025 to 12% by July as inflation pressure returned. The bank then raised the rate again to 12.25% from October 1.
That is a meaningful difference from Cambodia or Lebanon. Colombia is not defending a fixed exchange rate. The central bank is using interest rates primarily to control inflation, and the peso is allowed to absorb changes in market sentiment.
Oil remains important because it brings dollars into the country. Coffee, coal, tourism, gold, and other exports also contribute.
The peso belongs on this list by unit value, but it is one of the worst examples to use if someone wants to argue that a large USD conversion automatically signals a broken currency.
15. Burundian Franc (BIF)
Burundi has a more serious foreign-currency problem than the official 3,010 rate suggests.
The economy is small, exports are limited, and the country depends heavily on agriculture. Coffee and tea bring in foreign currency, while fuel, medicines, machinery, and manufactured goods create steady demand for dollars.
When the banking system cannot supply enough foreign currency at the official price, importers look elsewhere. That creates the same basic problem seen in Myanmar, although on a different scale. The published rate can stop describing the price that clears the market.
Burundi therefore deserves caution in a ranking like this. The official central-bank figure is verifiable, but a reader should not assume every business can actually obtain dollars at that price.
16. Tanzanian Shilling (TZS)
Tanzania rounds out the list, but it is not a natural crisis candidate.
Growth has remained above 5%, inflation has stayed within the central-bank target range, and the economy earns foreign currency from tourism, gold, agriculture, manufacturing, and other exports.
Fuel and machinery imports still create dollar demand, so the shilling can weaken when global energy prices rise or capital flows turn against emerging markets.
What separates Tanzania from Iran or Lebanon is the absence of a collapse in confidence. There is no enormous split between an official rate and a functioning market rate, and inflation is not destroying the currency from inside.
That makes Tanzania a useful stopping point for the list. Below this level, a large number of currencies trade at hundreds or low thousands per dollar, and the idea of calling every one of them “weak” becomes less useful.
Large Denominations and Real Depreciation Are Not the Same Thing
The best way to test the ranking is to compare today’s rates with older ones.
A currency that already traded at 20,000 units per dollar ten years ago is very different from one that moved from 1,500 to almost 90,000 during the same period.
| Currency | 2016 Rate per USD | 2026 Rate per USD | Increase in Local Units Needed for 1 USD | Reading |
|---|---|---|---|---|
| Lebanese Pound | About 1,507.5 LBP | 89,500 LBP | About 5,837% | Severe currency collapse |
| Vietnamese Dong | About 21,935 VND | 25,980 VND | About 18% | Large denomination with gradual depreciation |
| Indonesian Rupiah | About 13,308 IDR | 17,910 IDR | About 35% | Long-run depreciation without monetary collapse |
| Uzbekistani Som | About 2,965 UZS | 11,790.79 UZS | About 298% | Large repricing after foreign-exchange liberalization |
| Paraguayan Guarani | About 5,671 PYG | 5,850.05 PYG | About 3% | Nearly unchanged over a decade despite a large nominal number |
Lebanon stands out immediately. The dollar rate rose almost sixtyfold. That is real depreciation on a completely different scale from Vietnam or Paraguay.
Vietnam tells the opposite story. The dong already had five digits against the dollar in 2016. A 100,000-dong price looked large then and still looks large now, but the exchange rate moved by less than 20% across the decade.
Paraguay is even more striking. The guaraní is still around 5,850 per dollar, yet that is only slightly weaker than its 2016 average and much stronger than it was during parts of 2024 and 2025.
Uzbekistan needs a separate explanation because the country changed the exchange-rate system itself. The official rate jumped when authorities liberalized access to foreign currency in 2017. Part of the apparent depreciation was the government admitting a market price that had previously existed outside the official system.
What Central Banks Actually Do When Their Currency Comes Under Pressure
Central banks have several ways to respond, but none is free.
They can raise interest rates. Higher rates make local-currency savings more attractive and can reduce demand for imports, but loans become more expensive and economic growth can slow.
They can sell dollars from foreign reserves. That adds foreign currency to the market and can reduce sudden pressure, but reserves are finite.
Authorities can also tighten capital controls or restrict access to dollars. Iran, Myanmar, and Burundi show the downside. If the controlled rate becomes unrealistic, a parallel market develops and the country ends up with two prices for the same dollar.
Indonesia and Colombia represent a more market-based response. Both allow substantial exchange-rate movement and use interest rates, reserves, and market operations to limit inflation or disorderly swings rather than promising one fixed dollar price.
Oil Prices Can Hit Weak Currencies Twice
View this post on Instagram
Fuel-importing countries face a particularly nasty combination when oil rises and their own currency falls at the same time.
Suppose a barrel of imported fuel becomes 20% more expensive in dollars. If the local currency also loses 10% against the dollar, the domestic cost rises by more than the oil-price increase alone.
Transport companies then pay more for fuel. Farms and factories pay more to run equipment. Delivery costs increase. Food prices follow.
Laos is especially exposed to that chain because it imports fuel and already carries heavy foreign-currency debt. Uzbekistan is also a net importer of oil and gasoline despite being a major producer of other energy resources.
Exports Can Strengthen a Currency, but the Type of Export Counts
Vietnam, Paraguay, Guinea, Mongolia, and Tanzania all earn foreign currency from exports, but their export structures are not equally safe.
Vietnam sells a wide range of manufactured products. Paraguay relies heavily on agriculture and electricity. Mongolia depends on coal and copper. Guinea depends on mining.
A diversified export base spreads the risk. A country built around one or two commodities can lose foreign-currency income quickly when prices fall.
That is why Mongolia watches China so closely and Guinea’s outlook is tied to Simandou. The exchange rate responds not only to how much a country exports but also to what it sells and who buys it.
Trade flows matter on both sides of the equation, and the US trade deficit is one example of how large import and export imbalances shape demand for foreign currencies.
Foreign Reserves Show How Much Breathing Room a Country Has
Foreign reserves are the dollars, euros, gold, and other external assets held by a central bank.
A large reserve stock gives policymakers more room to pay for imports, meet external obligations, and smooth sudden currency moves.
Indonesia had about $146.5 billion in reserves at the end of August 2026. Uzbekistan had roughly $70 billion in January, although gold accounted for 86% of that amount. Paraguay had about $11 billion in net international reserves at the end of June.
The raw total still needs context. A large country imports more than a small one, so analysts also compare reserves with monthly imports, short-term external debt, and other obligations.
Low reserves do not guarantee a crisis, but they leave a central bank with fewer options when dollar demand suddenly rises.
Foreign reserves can include government securities as well as cash and gold, which is why understanding who holds US debt also gives useful context for the global reserve system.
Why Redenomination Can Change the Ranking Without Making Anyone Richer
A country can remove three zeros from its currency and jump hundreds of places in a nominal ranking overnight.
If 1,000 old units become one new unit, a salary of 5,000,000 becomes 5,000. A product costing 100,000 becomes 100. An exchange rate of 20,000 per dollar becomes 20.
Purchasing power does not change at the moment of conversion.
Sierra Leone is the clearest warning for currency lists. In 2022, one new leone replaced 1,000 old leones. Rankings that still list Sierra Leone at around 20,000 units per dollar are comparing the retired denomination with current currencies.
That is why redenomination history has to be checked before calling any currency one of the weakest in the world.
What the Ranking Says, and What It Does Not
The list is useful for one thing. It shows which currencies have the smallest individual unit when compared with the dollar.
It does not tell you where people are poorest, where inflation is highest, or which economy is weakest.
Iran and Lebanon rank high because their currencies suffered enormous losses. Vietnam ranks high because one dong is simply a very small unit. Paraguay ranks high despite a strong recent appreciation. Uzbekistan carries the legacy of a major exchange-rate reform.
Those are four completely different economic stories hiding inside the same table.
For readers trying to judge the health of a currency, the next numbers to check are inflation, five-year or ten-year depreciation, foreign reserves, interest rates, current-account flows, external debt, and any gap between the official rate and the price available in the market.
Sources
- International Monetary Fund, World Economic Outlook
- World Bank, World Development Indicators
- World Bank, Global Economic Prospects
- Bank for International Settlements, Exchange Rate Statistics
- IMF Data, Macroeconomic and Financial Series